

1.- DONATIONS AND ISFUT
Transitional regularization windows
- Donations: 50% reduction of the assessed tax, on a one-time basis, for one year,subject to family, net-worth, and formalization requirements.
- Substitute Tax on Profits Accumulated in the FUT — Taxable Profit Fund (ISFUT): 10% single tax to regularize outstanding STUT (Total Taxable Profit Balance), FUR (Reinvested Profits), and excess-withdrawal balances, within an eight-month period. The associated tax credits would be extinguished.
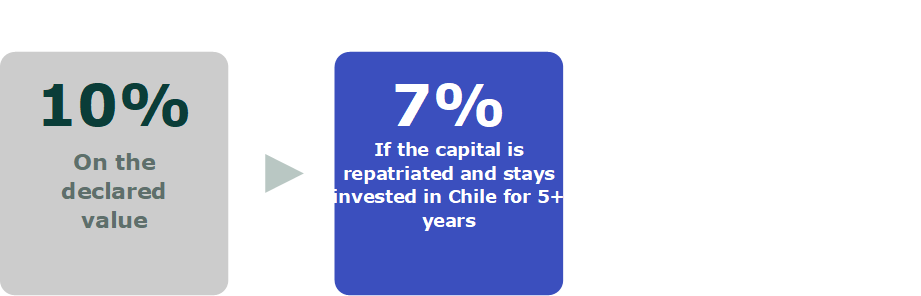
2.- ASSETS HELD ABROAD
Single tax to regularize assets held abroad
3.- ASSETS HELD ABROAD
Waiver of tax and municipal debts
- Tax debts: The Treasury may grant payment agreements and waive interest and penalties on obligations overdue through December 31, 2025. Does not apply to large companies
- Municipal debts: Twelve-month regularization period for business licenses (patentes), waste-collection fees, vehicle circulation permits, and other obligations, with a waiver of interest and penalties.
4.- TAX ENFORCEMENT AND COLLECTION
Broader powers for the SII and the Treasury
- SII: May request and cross-reference individually identified information held by other State Administration bodies.
- Treasury: Could take over administrative and judicial collection of municipal business licenses and waste-collection fees. In addition, the Treasury could withhold tax refunds and apply them against those debts.

