

1.- CORPORATE INCOME TAX (IDPC)
Gradual reduction of the corporate income tax (IDPC) rate under the following schedule:
| Fiscal Year | IDPC Rate | Tax Return Filing Year |
| 2026 | 27% | 2027 |
| 2027 | 25.5% | 2028 |
| 2028 | 24% | 2029 |
| From 2029 | 23% | 2030 onward |
Transitional adjustments to the monthly provisional tax payment (PPM) rate are also contemplated to accompany the tax reduction.
What would happen to the SME rate?
a) No permanent change: The SME rate would remain unchanged under the transitional regime currently in force, which sets it at 12.5% in 2026 and 2027, 15% in 2028, and aligns it with the rate applicable to other companies from 2029 onward.
b) SME PPM: Decreases from 0.25% to 0.23% starting in 2029.
c) What’s pending?: Adjustments to the 12.5% SME rate would be addressed in a separate legislative bill.
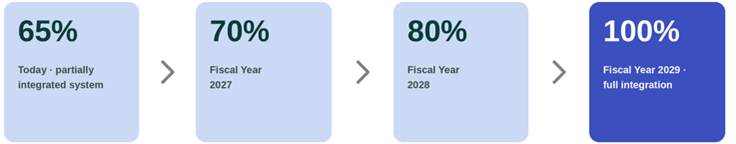
2.- REINSTATEMENT OF FULL TAX INTEGRATION
This will phase in gradually over the coming years:
3.- TAX INVARIABILITY (STABILITY)
New regime for investments of USD 50 million or more
| Investment Amount | Stability Period |
| USD 50 M to under USD 100 M | 10 years |
| USD 100 M to under USD 350 M | 15 years |
| USD 350 M or more | 20 years |

